

Two homes on the same road can get very different quotes.
The short answer: Much of Black Forest and western Monument sits in the wildland-urban interface, where homes meet forest and grassland. Insurers price that risk, so premiums can be higher, some carriers limit new policies, and coverage can vary a lot from one property to the next. Owners and buyers can help by documenting wildfire mitigation, hardening the home, shopping coverage early and knowing that the Colorado FAIR Plan exists as a last resort.
By Brennan Wolff, Broker, Realtor®
I grew up between Monument and Black Forest, and the 2013 Black Forest Fire still shapes how buyers, owners and insurers look at this area. Wildfire risk doesn't make these places any less special to live in, but it does mean insurance deserves more attention here than it would in town.
Here's what owners and buyers should know.
Why is home insurance harder to get in wildfire areas?
Insurers use wildfire risk models to score each property. Those scores look at things like vegetation, slope, access and nearby fuels. A higher score can mean a higher premium, a larger deductible or, with some carriers, a decision not to write a new policy at all.
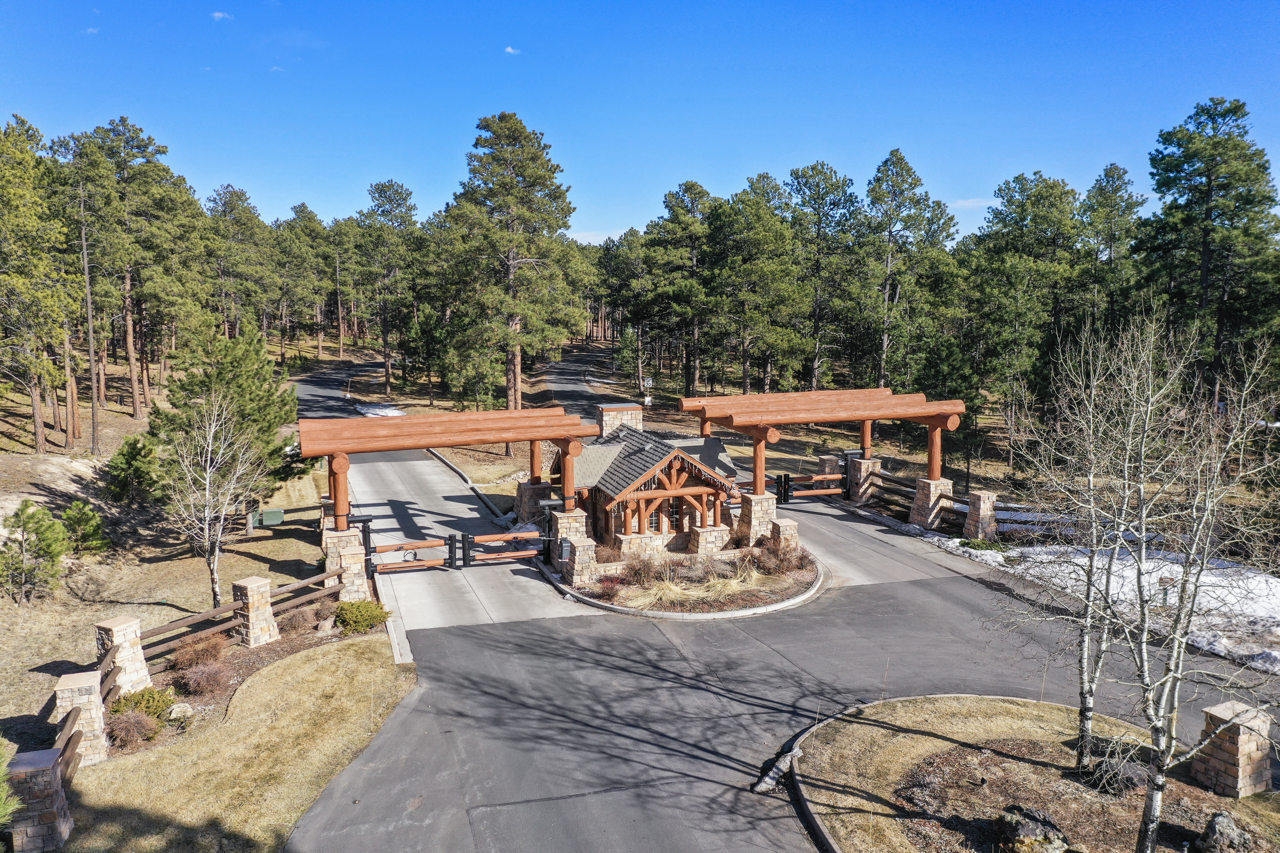
Two homes on the same road can get very different quotes. Tree spacing, roof material and how close the forest comes to the house all make a difference.
What has Colorado done about wildfire insurance?
Colorado has passed several laws in recent years aimed at availability and transparency. According to The Colorado Sun:
- The Colorado FAIR Plan, created by a 2023 state law, is an insurer of last resort for homeowners who have been turned down by the regular market. It covers the home's actual cash value rather than full replacement cost, and it isn't inexpensive.
- A 2026 law requires insurers to explain a customer's wildfire risk score in plain language.
- The Strengthen Colorado Homes program, created in 2026, is set up to fund grants for homeowners who harden their homes. As of mid-2026, its board was still forming, with grants expected to start in 2027.
Rules are still evolving, so check the Colorado Division of Insurance for the latest.
How can you lower your wildfire risk and help your insurance?
The Colorado State Forest Service organizes mitigation around the home ignition zone, starting at the house and working outward.
- The first 5 feet: Keep it clear of anything that burns. Swap bark mulch for rock, move firewood away from the house and clean pine needles off the roof and out of gutters.
- 5 to 30 feet: Thin trees so their crowns don't touch, remove ladder fuels like low branches and brush, and keep grass short.
- 30 to 100 feet and beyond: Thin dense stands of trees and break up continuous fuel.
Home hardening matters too:
- A Class A fire-rated roof
- Ember-resistant vents
- Noncombustible siding near the ground
- Enclosed decks and eaves
Keep records and photos of everything you do. Ask your insurer whether they offer mitigation discounts, and ask your local fire district whether it offers home wildfire assessments.
What should buyers do?
- Get insurance quotes in the first few days of your inspection period. Don't wait until the week before closing. Availability and price can change your decision.
- Ask the seller for mitigation records. Thinning, assessments and roof information all help.
- Look at the property with fire in mind. How close is the forest to the house? How long and narrow is the driveway? How quickly could a fire truck get in and turn around?
- Work with an independent agent. An agent who can quote several carriers is often the fastest way to find coverage in a wildfire area.
What should sellers do?
If you're planning to sell, mitigation work is one of the best things you can do before listing. It makes the property easier to insure, which makes it easier to sell. Gather receipts, photos and any assessment reports, and share them with buyers early. The Seller's Guide covers this in more detail.
Frequently asked questions
Is Black Forest a high wildfire risk area? Much of it sits in the wildland-urban interface, especially the heavily wooded western side. Risk varies a lot from one property to the next.
What is the Colorado FAIR Plan? An insurer of last resort created by state law in 2023 for homeowners who can't find coverage elsewhere. It typically covers actual cash value, not full replacement cost.
Does wildfire mitigation lower insurance costs? It can help with some insurers and may make a property easier to insure. Ask your insurer what discounts they offer.
When should buyers shop for insurance? Right away. Get quotes in the first few days of your inspection period.
Questions about a property you own or want to buy?
I'm happy to walk a property with you and point out what buyers and insurers will notice. Explore the Black Forest guide and the Tri-Lakes guide, or reach out to me directly.
This post shares general information, not insurance or legal advice. Talk with a licensed insurance agent about your specific property.
Sources: The Colorado Sun, wildfire insurance and homeowner regulations · Colorado State Forest Service, The Home Ignition Zone · Colorado Division of Insurance
Check out this article next