

Your equity is what your home is worth today, minus what you owe. Here's how to find it and put it to work.
The short answer: Your home equity is the difference between what your home would sell for today and what you still owe on it. To estimate it, start with a realistic market value, not an online estimate, then subtract your loan balance and any other liens. Many homeowners use equity to move up to a larger home or acreage, fund updates, or build a financial cushion. Most lenders want you to keep at least some equity in the home if you borrow against it.
By Brennan Wolff, Broker, Realtor®
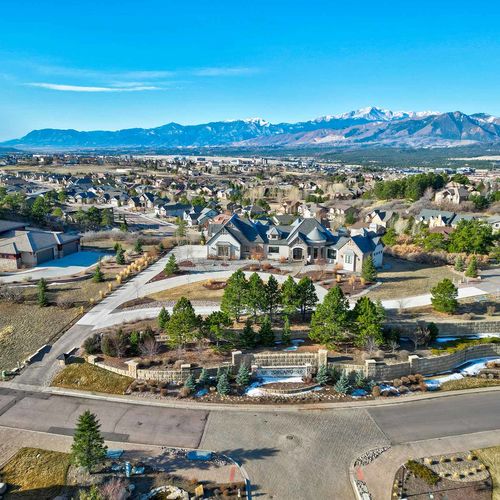
A lot of homeowners on the north end have owned long enough to build real equity. But "equity" can feel abstract until you put a number on it, and that number is what makes the next decision possible, whether that's moving, updating or simply planning ahead.
Here's how to figure out where you stand.
How do you calculate your home equity?
The math is simple:
Home equity = what your home would sell for today − what you owe
What you owe includes your mortgage balance plus any home equity loan or line of credit. Your lender's statement shows those.
The harder part is the first number. Online estimates can miss in either direction, especially in neighborhoods where views, lot position, updates and acreage vary a lot. This post on why similar homes sell for different prices explains why. A local broker's opinion of value, based on recent sales and the home itself, gives you a more realistic starting point.
What about the costs of selling?
If you're thinking about selling, what you'll actually walk away with is your net proceeds, which is your equity minus selling costs like commissions, title fees, any repairs or prep, and any concessions to the buyer. A good estimate of net proceeds is the number to plan around if you're moving up.
How can you use your equity?
Move up. This is the most common use I see. Equity from your current home can become the down payment on a larger home, a different neighborhood or acreage in Black Forest or Monument. In some cases, it can even cover the next home outright. My move-up guide walks through how to time the sale and purchase.
Right-size. If your home has more space or land than you need, equity can help you move into something that fits how you live now, sometimes with money left over.
Update your current home. If you're staying, a home equity line of credit (HELOC) or loan can fund projects. Focus on updates that matter for how you live and that buyers will value later.
Build a cushion. For some homeowners, simply knowing their equity is part of long-term financial planning.
What are the ways to access your equity without selling?
- A HELOC works like a credit line secured by your home. You borrow as needed, often with a variable rate.
- A home equity loan gives you a lump sum at a fixed rate.
- A cash-out refinance replaces your current mortgage with a larger one and gives you the difference in cash. If your current rate is low, this may not make sense.
Each option has costs and risks, because your home secures the debt. Most lenders require you to keep a portion of your equity in the home. Talk with a lender and a financial advisor before you borrow.
Frequently asked questions
How do I find out how much equity I have? Subtract what you owe from a realistic estimate of what your home would sell for today. A broker's opinion of value is more reliable than an online estimate.
Can I use my equity to buy another home? Yes. Many move-up buyers use equity from their current home, either by selling first or with a HELOC or bridge loan.
What's the difference between a HELOC and a cash-out refinance? A HELOC is a separate credit line. A cash-out refinance replaces your mortgage with a new, larger one.
How much equity do I need to keep? It depends on the lender and loan type. Ask your lender before you borrow.
Want to know what your equity looks like?
I'm happy to give you a realistic read on your home's value and what you'd net if you sold. Request a home valuation or reach out to me directly.
This post shares general information, not financial advice. Talk with a licensed lender or financial advisor about your situation.
Check out this article next