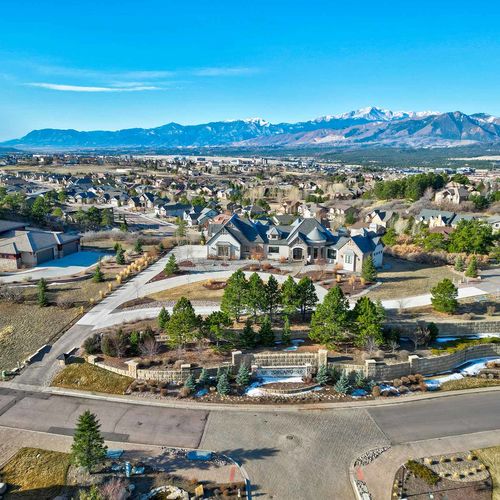


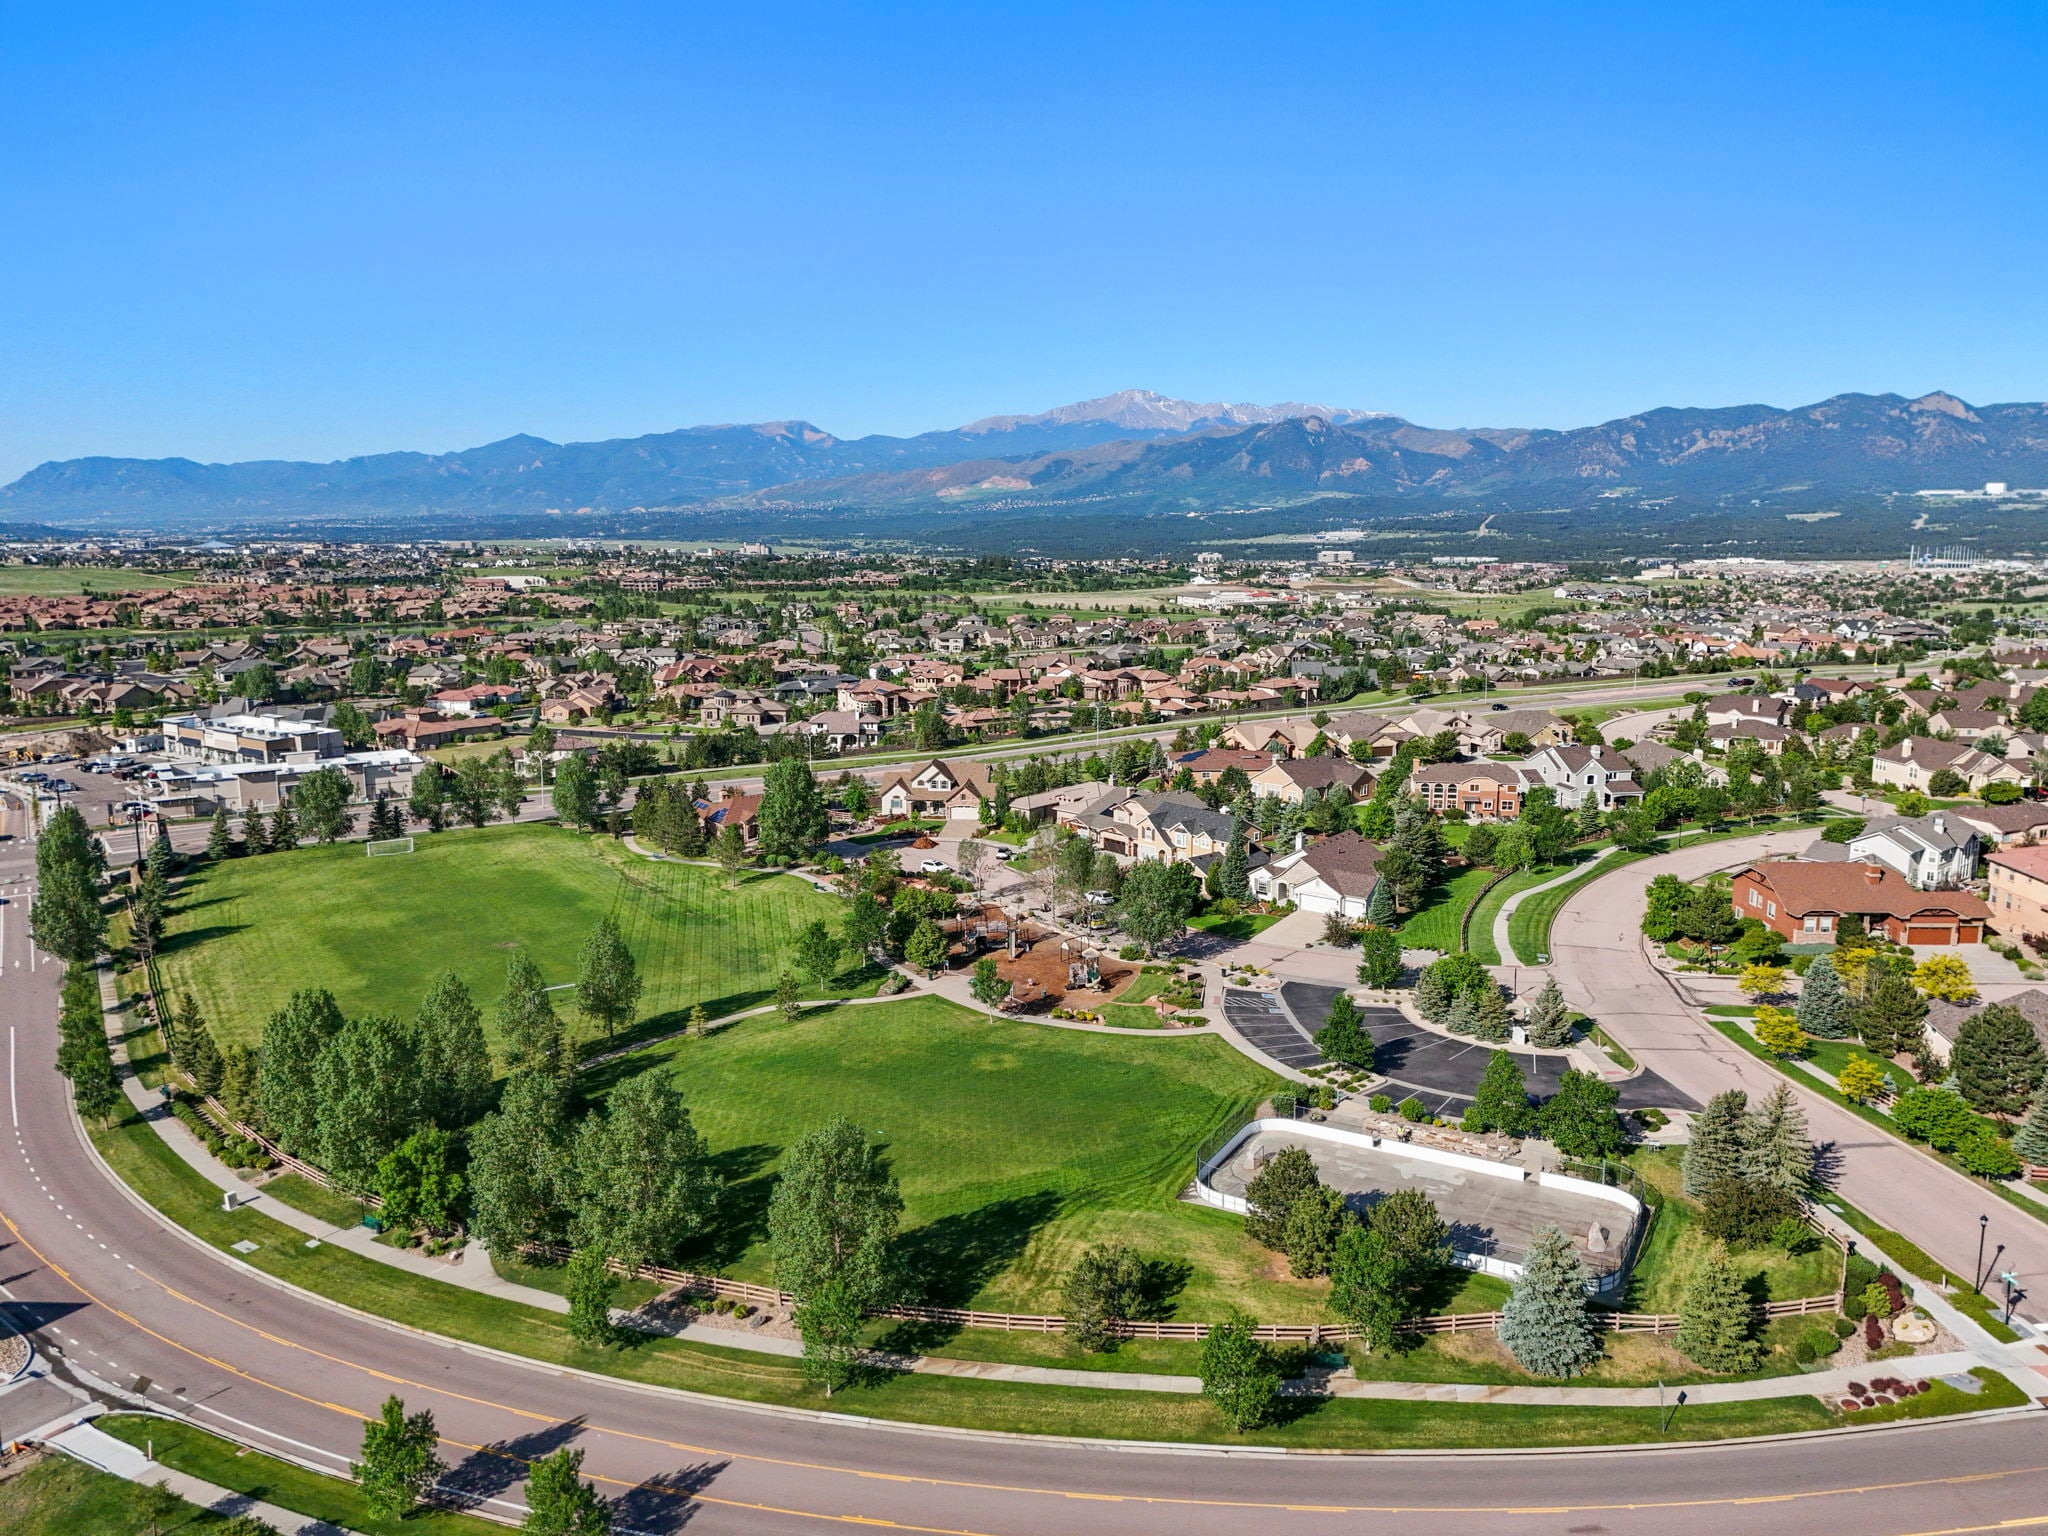
The move-up guide for Northern Colorado Springs, Monument and Black Forest.
The short answer: Moving up without two mortgages or nowhere to go starts with three things: knowing your numbers, choosing a financing path that fits, and building your timeline around how long homes like yours actually take to sell. Most move-up buyers either use their equity to buy first (with a HELOC or bridge loan), sell first and arrange a short rent-back, or make an offer contingent on selling. Which one works best depends on your finances and the price range and neighborhood you're moving into.
By Brennan Wolff, Broker, Realtor®
If you own a home on the north end and you're outgrowing it, you're in good company. A lot of our clients are moving up, whether from Gleneagle or Briargate into Flying Horse, from a Monument subdivision into Woodmoor, or from town out to acreage in Black Forest. The hardest part usually isn't finding the next house. It's coordinating the sale and the purchase.
Here's how to do it without losing sleep.
For buyers: planning the next purchase
Start with your numbers
Before you fall for a listing, get clear on three things:
- Your equity. What your current home should realistically sell for today, minus your loan payoff and selling costs.
- Your comfortable payment. Not just what a lender approves, but what you actually want to spend each month.
- Your target range. Whether your next step is a modest move up or a bigger jump into a different neighborhood or property type.
A good planning session should give you a current market analysis on your home, an estimated net proceeds sheet and payment ranges for a few target prices.
Choose a financing path
Your equity is your biggest advantage. The question is how to use it to bridge from one home to the next.
- A home equity line of credit (HELOC) on your current home can fund your down payment on the next one. You pay it off when your home sells. It usually needs to be in place before you list.
- A bridge loan uses your current home's equity to help you buy before you sell, usually for a short term.
- Carrying both payments for a short window works if you qualify for both and have the cash flow.
Each comes with costs and risks. Talk with a lender early and compare scenarios before you write an offer.
Match your offer strategy to the market you're shopping
Whether you can write an offer contingent on selling your home depends on the price range and neighborhood.
- In steady, mid-range markets, some sellers will accept a home sale contingency, especially if your home is already listed or about to be.
- In higher price ranges and newer, larger homes, sellers often favor offers without a home sale contingency, or ones where your home is already under contract.
A common plan looks like this: get your current home fully ready to list, line up photos in advance, shortlist the homes you'd buy, then either write with a well-structured contingency and a quick list date, or list first and write as soon as you have a buyer.
For sellers: setting up the sale
Build your timeline backward
Start with when you want to be in the new home and work back from there:
- Your target move-in date
- The closing period, usually 30 to 45 days after going under contract
- Typical time on market for homes like yours, at your price point, right now
- Your prep window for repairs, decluttering and photos
The Market Update shows current days on market by zip code, and I'm happy to pull numbers for your specific neighborhood.
Prep for speed, not perfection
Your goal is a quick, clean "yes" from the right buyer, not a magazine shoot. Focus on first-impression spaces like the entry, kitchen, main living area and primary bedroom, plus paint, lighting and basic repairs. My post on improvements that pay off before selling covers what to prioritize.
Price to sell, not to test the market
For move-up sellers, overpricing costs more than money. A home that sits loses momentum, invites price cuts and can leave you watching the home you wanted go to someone else. Pricing right from day one gives you predictability, and predictability is what makes the next purchase work. This post on pricing explains how I approach it.
Negotiate for time
A short rent-back after closing, or flexible closing dates, can let you sell first without moving twice. These terms are often worth as much to a move-up seller as a slightly higher price.
Frequently asked questions
Can I buy a new house before selling mine? Yes, often with a HELOC, a bridge loan or by qualifying to carry both payments for a short time. A lender can tell you which options fit.
What is a home sale contingency? A clause that makes your purchase depend on selling your current home. It protects you but can make your offer less competitive in some markets.
What is a rent-back? An agreement that lets you stay in the home you sold for a short period after closing, usually so you can move straight into your next home.
Should I sell first or buy first? It depends on your finances, your comfort with risk and how competitive the market is in the range you're buying in.
Planning a move up?
I'll map out your numbers, timing and financing options so you can see exactly how a move up could work for you. Read Buy with Us and Sell with Us, or reach out to me directly.
This post shares general information, not financial advice. Talk with a licensed lender about your options.
Check out this article next